We have summarised the whole investment opportunity, from the market to the investment structure, in a presentation for professional investors (in English).
For professional investors
The capital side in brief
Koykan is an international fast casual restaurant chain: quick, healthy and affordable food. The network operates in several European countries and is expanding through local operating partners who build and run restaurants under the Koykan brand in their own market.
The build-out is not funded by borrowing at group level but through a separate capital structure. Investors put their capital either into the companies that build and develop the restaurant business in the first phase, or into those that own the restaurants in the second phase and pay out their earnings. This page describes how that capital side is arranged, who charges what and who verifies it.
It is intended for professional and qualified investors, family offices, mezzanine funds and institutions. The minimum investment at this level is EUR 100,000. The rest of the website describes the channels for retail investors.
For the market and the opportunity itself, see the home page, and for the company behind it all, open Why Koykan?
How the model works
The Growth side funds the construction of restaurants and holds them until they begin to earn steadily. The Yield side then buys them, holds them for the long term and pays their earnings out to its investors. This sale from one side to the other is called the transfer.
The transfer is not the only exit. An established location can also be sold by the Growth side to a third party at the market price, and it does not wait for the transfer if a buyer appears sooner. The Yield side has no right of first refusal.
In both cases, the sale proceeds go back to the investors on the Growth side, as a return of the capital invested and the profit.
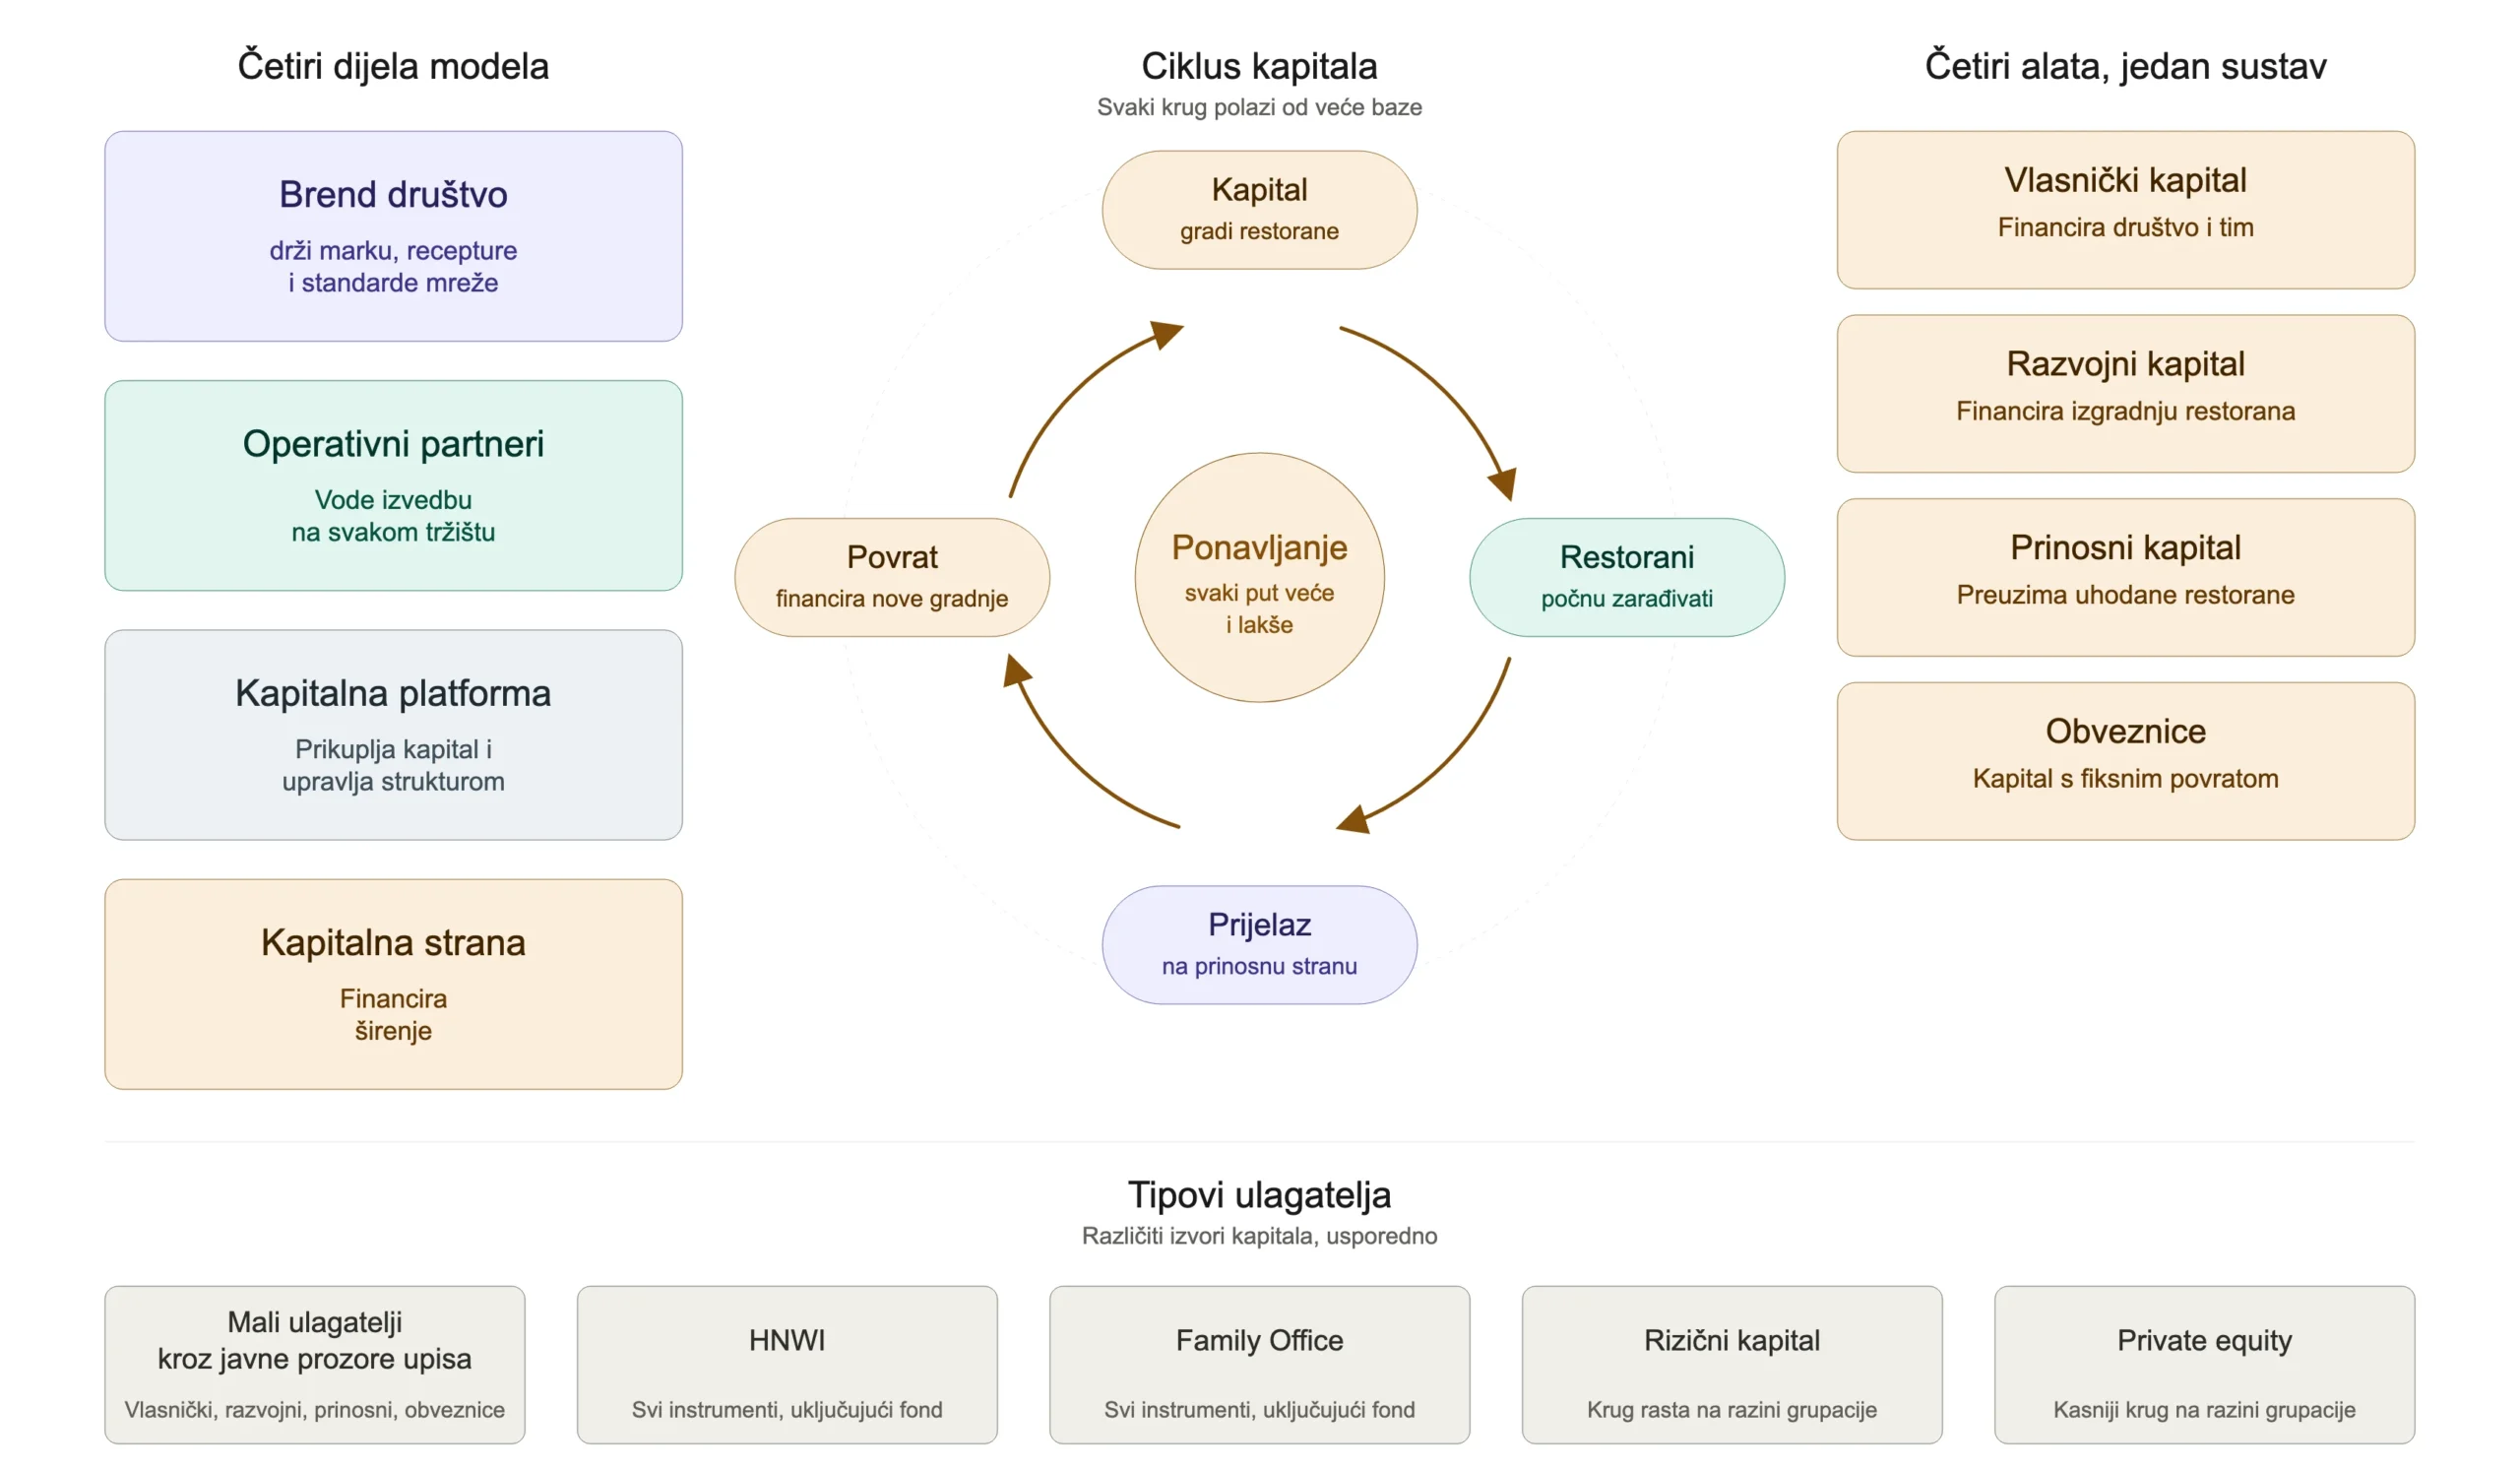
The diagram covers the whole model and all types of investor.
Current rounds
The Growth programme funds 20 new restaurants, with a target return of 1.5 to 2 times the capital invested, or an IRR of 20 to 35% a year, over a cycle of 18 to 30 months per location. The Yield programme opens the first portfolio of established restaurants, with an indicative dividend of 8 to 12% a year and a target close in the fourth quarter of 2026. New rounds open every year, totalling EUR 10 to 30 million. According to the model’s illustration, the Growth side generates about EUR 1.75 for every euro invested, after tax at company level, the partners’ share and a reserve for one restaurant in ten that fails.
Entry is through local capital partners in your own country, from EUR 100,000, and through the private investor club Koykan Capital Partners GmbH, from EUR 1 million. The Group is also preparing to establish an alternative investment fund (AIF) in the Netherlands; the fund has not yet been established and its establishment depends on approval from the competent authority. Target returns are estimates, not guarantees.
Four things that set this structure apart
A single fee in the entire structure
The fund’s fees will be set out in its documentation once it is established.
The capital platform above it charges neither a management fee nor carried interest, and has no preferred return or sponsor catch-up. It re-invoices its own cost of carrying out the work to the capital companies at cost, with no margin, and charges the holding companies nothing. Distributions are made in proportion to paid-in capital.
The Group comes in on the same terms
The Group subscribes for stakes in the same companies as the investors, in the same class and at the same published price per unit of capital. There is no preferred class, priority return or earlier exit.
Its return is whatever its own stake earns, at the same moment and by the same formula as everyone else’s. The Group’s and the investors’ interests therefore align by construction, not by declaration.
The transfer price is known in advance
Every sale from the Growth side to the Yield side is calculated using a published formula, the same for both sides. The formula is set so that the Yield side, which buys the location, earns about 10% a year from the restaurant’s profit, and it is applied to every location in the same way. For a restaurant that generates about EUR 90,000 of EBITDA a year, after all operating costs, that means a price of about EUR 850,000.
The formula applies to sales to the Yield side; sales to a third party are made at the market price. The investor therefore knows in advance by what rule their position is valued, regardless of when they come in and which build round it belongs to. If a location needs more time to bed in, it is sold later, but the formula stays the same.
The check is done by someone outside the Group
An independent firm, engaged separately from the auditors of the companies whose figures it uses, calculates the value of the asset and the formula price and confirms that both sides are valued by the same rule. Without its written confirmation, no transfer is carried out.
It also confirms once a year that the fee regime is being observed. Its fee is borne by the capital platform, not by the investors, and it is fixed. Once established, the fund will be managed by an external licensed manager, with a separate depositary and administrator.
What the investor holds and how they exit
Ownership, not a claim
The investment is not a secured loan but a stake in the company that owns a specific restaurant. Each location is a separate company, with its own equipment, lease and brand licence.
The kitchen and counter lines are standardised and portable, so they retain their value outside that location too.
Capital comes back in instalments
On the Growth side, liquidity comes from the model itself. Capital is returned as individual locations are sold, to the Yield side at the published formula or to a third party at the market price, so gradually, over the life of the investment, rather than through a single exit at the end.
On the Yield side, the return is ongoing, through an annual dividend, with repurchase windows within a 10% reserve set aside for buying back shares. A stock exchange listing is being considered for the Yield companies, which would give the share a visible price and regular trading.
Who is already on board
More than 500 investors have funded the platform to date. Cumulatively, around EUR 6 million has been invested in developing the network, with several strategic investors in the ownership structure.
There is also a multi-year record of coupons paid on time across the previous bond issues.
Documentation
Available under a confidentiality agreement.
- Group structure and ownership chart
- Historical financial statements and projections
- Cap table by tier
- Valuation methodology and report
- The transfer formula and its calibration
- Unit economics model and assumptions
- Articles of association of the capital companies and class rights
- Risk register and conflicts of interest register

Contact
Investor relations
Leave your details. Investor relations will contact you personally and arrange an introductory meeting within 48 hours. After the meeting, a data room opens under an NDA, with the complete offer documentation, and a tour of the restaurants is possible on request.
This page does not constitute an offer or an invitation to invest. The terms of each instrument are set exclusively by the relevant offering documentation.